Does the AI Dream have a Budget?
Welcome to AI8’s weekly newsletter, your ultimate source for curated insights and updates from the dynamic world of venture capital!
From billion-dollar rounds to market-defining shifts, we deliver the intelligence powering the global investment landscape, moving investors and innovators forward. At 8alpha.ai, we’re not waiting for the future of capital, we’re building it. Stay sharp, stay curious, and stay ahead.
STARTUPS
ROUNDS AND UNICORNS
The Week’s 10 Biggest Funding Rounds: AI And Energy Top A Busy Lineup Of Large Rounds (Crunchbase, 5 minute read)
Axiom Solutions International (Cloud and Power Infrastructure): Austin-based Axiom, a private cloud and power infrastructure company spun out of Flex, secured $2 billion in new financing as General Catalyst and Koch Equity bought shares from Flex at an initial enterprise value of $37.5 billion, with Flex planning to list Axiom as an independent public company early next year
TypeSafe AI (Foundational AI):San Francisco-based TypeSafe AI, developer of the recently launched Jev AI model, raised $870 million with Andreessen Horowitz as the largest investor and Sequoia Capital also participating, reportedly at a $7.5 billion valuation
Oratomic (Quantum Computing):Pasadena-based Oratomic, which is building fault-tolerant quantum computers, raised $475 million led by Arch Venture Partners, Spark Capital, Khosla Ventures, Index Ventures, General Catalyst, and Bezos Expeditions, following a $300 million raise in July
SignSplit (Data and Content Protection): New York-based SignSplit, which provides tools for protecting and licensing human-generated data, emerged from stealth with $400 million in seed funding backed by W Group, setting a $1 billion valuation for the company founded in 2024
Vinci (AI for Engineering): Palo Alto-based Vinci, developer of an AI computational platform for hardware engineers, closed $250 million in Series B funding at a $1.5 billion valuation, led by Advent, Temasek, and Xora
North America’s Startup Funding Falls In Q3 As AI Giants Eye The Public Markets (Crunchbase, 5 minute read)
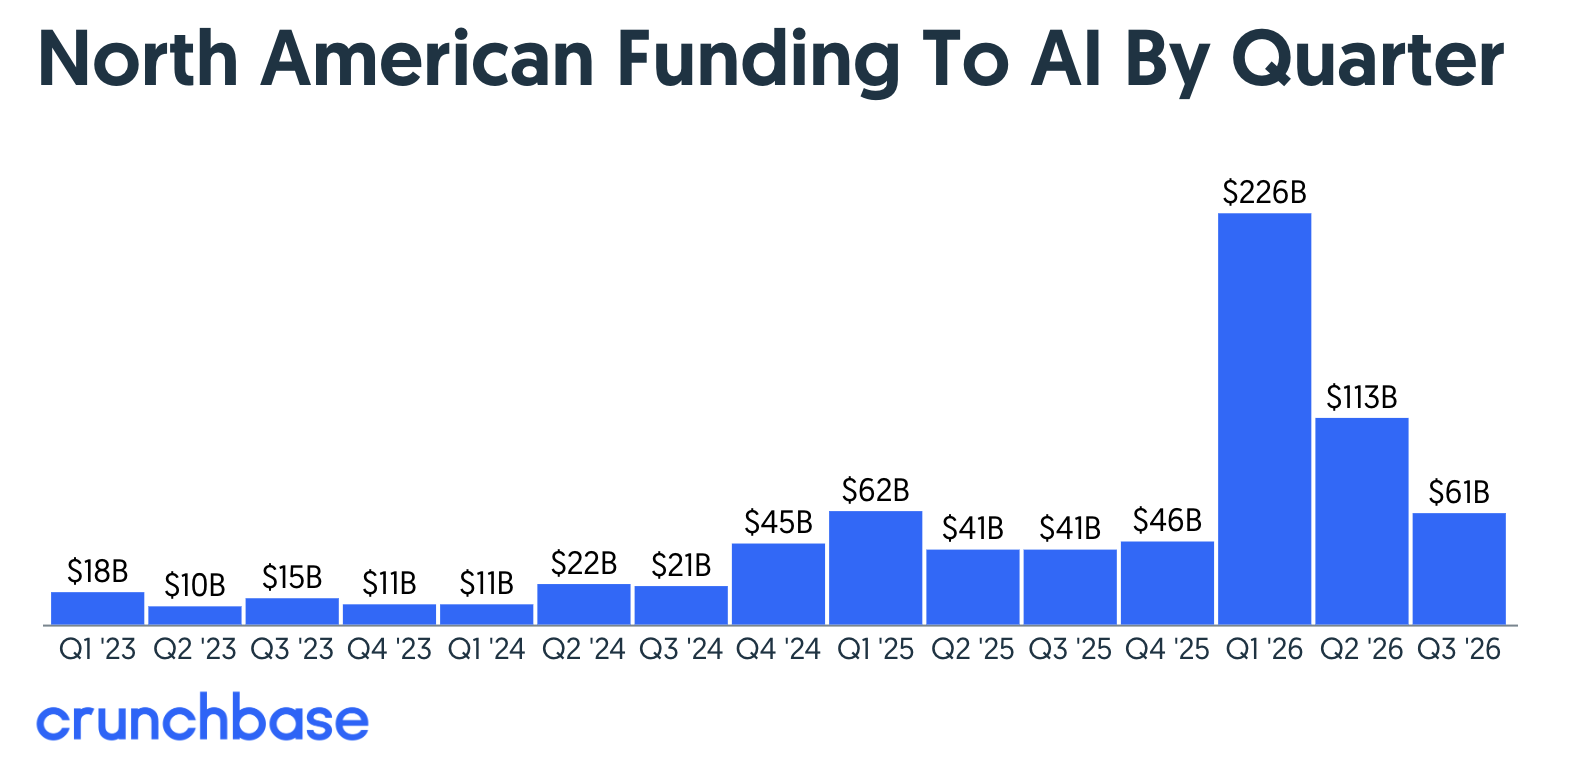
North American startup funding fell to $92 billion in Q3, down 35% from Q2 but up 50% year over year, a dip driven by the absence of new OpenAI and Anthropic megarounds rather than a broad weakening in venture conditions. AI took roughly two-thirds of funding, or $61 billion, one of the highest totals on record. Late-stage funding totaled $66.45 billion, led by Databricks ($5 billion), Crusoe ($3.9 billion), The Boring Co. ($3 billion), and Cognition ($2 billion), while early-stage funding reached $20.6 billion and seed about $5 billion. On exits, there were 11 North American acquisitions priced at $1 billion or more, led by Nvidia's $12.93 billion purchase of Hugging Face, while the IPO market was light, with 17 venture-backed listings raising just under $4 billion
More than a dozen startups raised late-stage rounds of $1 billion or more
AMD's roughly $8.2 billion acquisition of World Labs and Stripe's roughly $7.5 billion deal for OpenRouter were the next largest M&A deals
Anthropic is reportedly eyeing a listing as early as November, while OpenAI is expected to debut in 2027
ECONOMIC SNAPSHOT
Fed officials are warning of more pain. Many Americans are already feeling it (CNN, 4 minute read)
With the Fed raising interest rates for the first time in three years, the article warns of a familiar tradeoff, echoing former Chair Jerome Powell's 2022 warning that taming inflation would bring "some pain." Inflation is driven mainly by fuel prices that have soared since the Iran war began in February, and the Fed is raising rates to keep higher energy costs from spilling into broader inflation. That risks weaker hiring and job losses, and since consumer spending makes up roughly two-thirds of the economy, a pullback could tip it into recession. The pain is uneven, with stock market investors cushioned while paycheck-dependent households are not, and Fed officials are split between patience and urgency, with the preferred inflation gauge more than a percentage point above the 2% target
New York Fed's John Williams said "there is no need for urgency," while Cleveland Fed's Beth Hammack warned waiting could make the fight harder
The September Consumer Price Index report, due Wednesday, may give officials key clues
US’s Reagan-era economic promises return as Trump’s AI-fueled growth fantasy (The Guardian, 6 minute read)
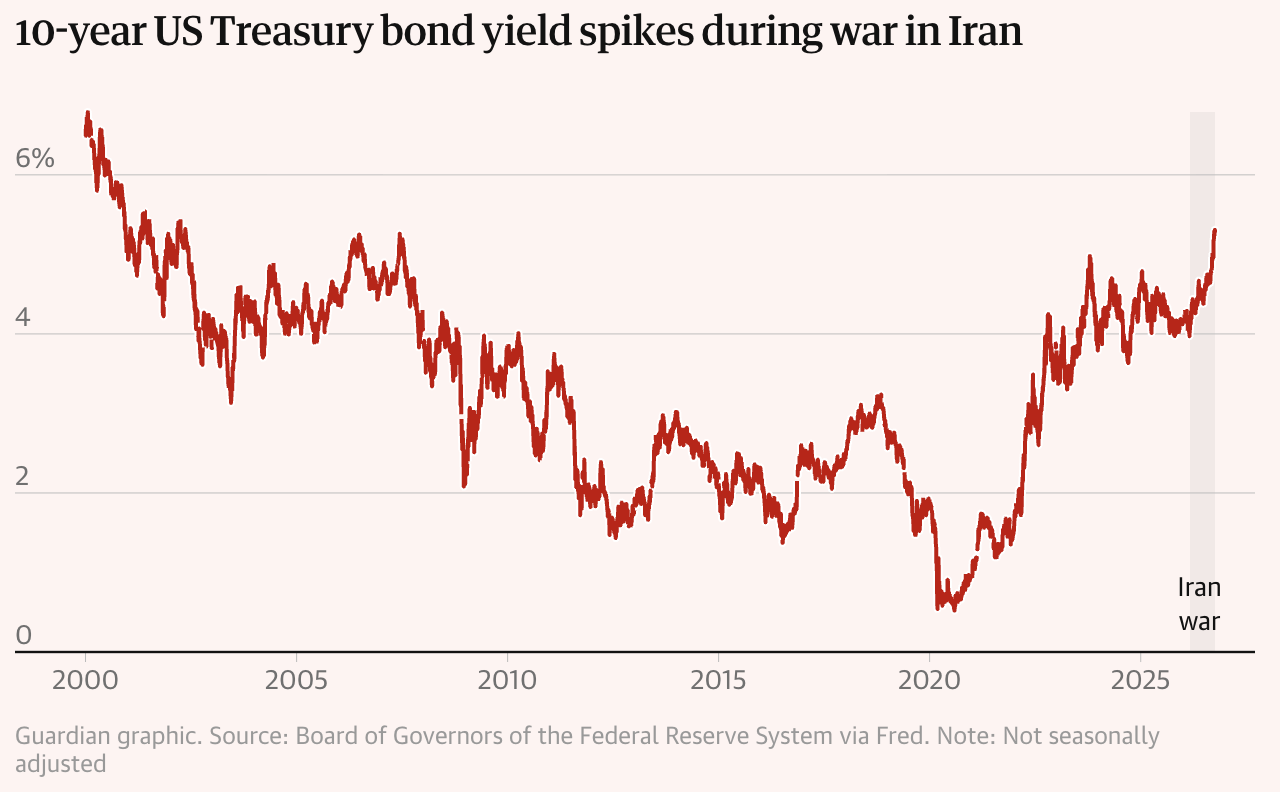
The old Republican promise that tax cuts pay for themselves has returned with an AI twist, as Treasury Secretary Scott Bessent counts on AI to deliver 3% annual growth and Trump claims growth will let the government handle $40 trillion in debt. Markets aren't convinced: the 10-year Treasury yield recently hit its highest in nearly 25 years, over a full percentage point above its pre-Iran-war level, while foreign central banks have cut back on Treasurys and AI companies borrowing for data centers compete for private capital. Interest payments already consume 3.3% of GDP versus a 50-year average of 2.1%, and the deficit has reached 6% of GDP, with a 3% deficit by 2036 requiring 4.4% annual growth and a balanced budget 7.2%. Even AI-driven growth would help the budget less than hoped, since it would shift income from labor to capital, which is taxed at roughly half the rate
Stanford's Hanno Lustig estimates data center owners need 45% annual revenue growth for seven years to break even on AI investment, estimated at $1.43 trillion this year
Six AI superscalers need $13.1 trillion to $18.7 trillion in added revenue over 10 years to cover their AI spending
Stabilizing the federal debt would require productivity growth of 2.5% a year, a rate the US has hit only once since 1959
3 charts sum up why many US households are struggling right now (Yahoo Finance, 2 minute read)
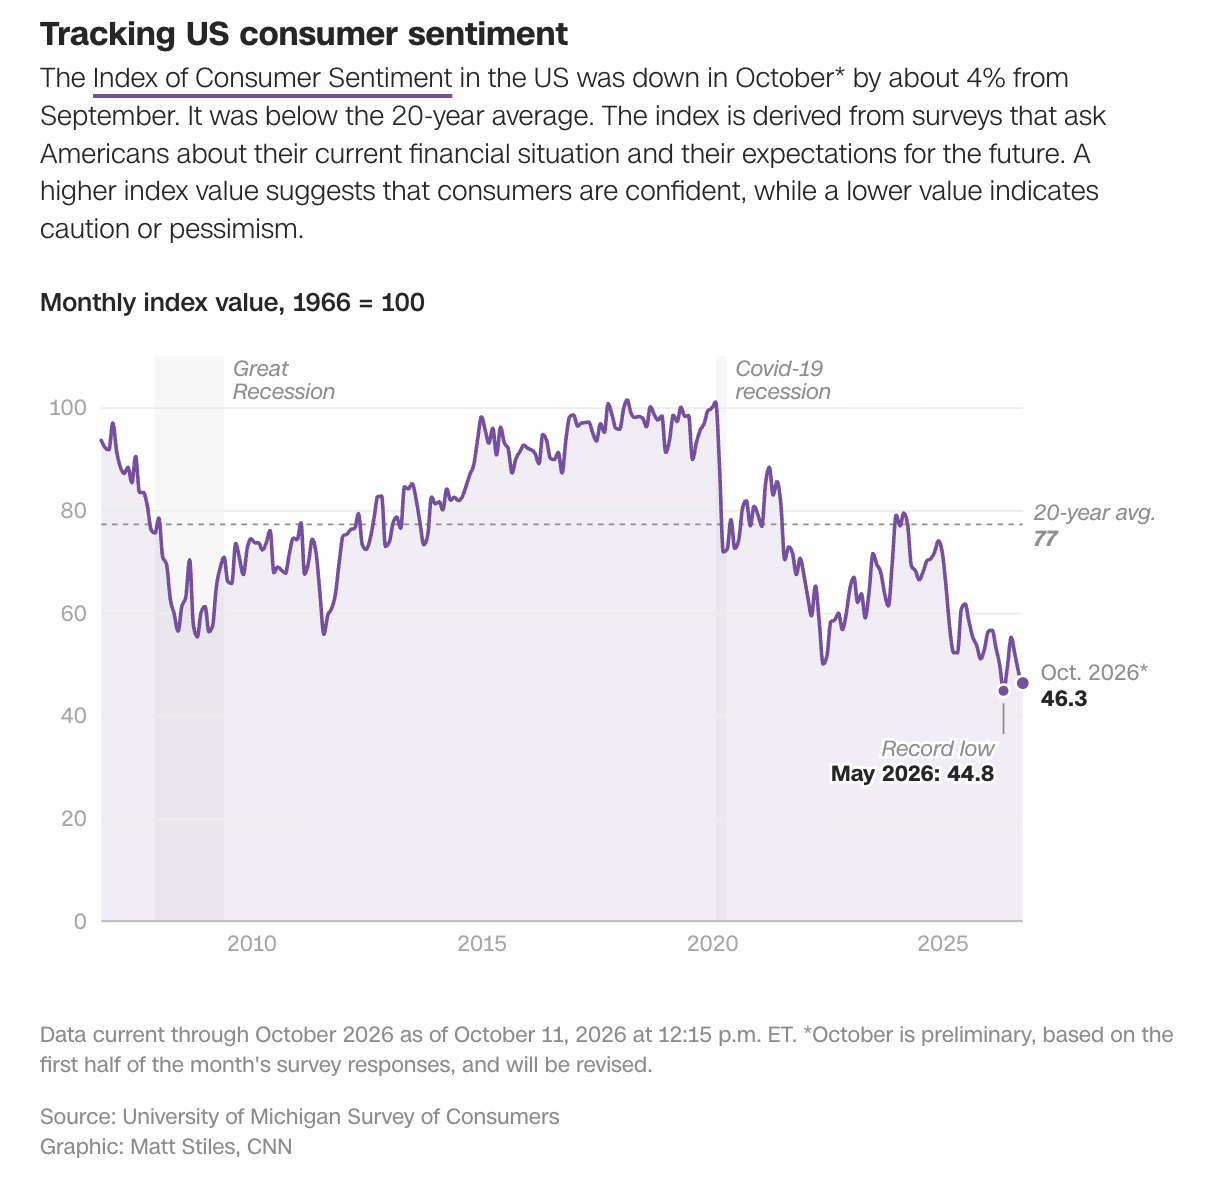
Consumer sentiment fell to 46.3 in October from 48.1 in September, a 1.8-point drop and a five-month low, according to the University of Michigan, even as the S&P 500 trades near a record high. Households are battling higher costs for gas, home heating fuel, and medical insurance, and the strain is showing up in third-quarter earnings from packaged food companies. PepsiCo slashed its full-year profit outlook and spice-maker McCormick reported sluggish demand. Wages are not keeping up: average hourly earnings rose just 0.1% month over month and 3% year over year in September, against 3.4% year-over-year inflation in August
Household debt now tops $18 trillion, per Goldman Sachs
Personal savings rates are below their long-term average, though the article gives no exact figure
PepsiCo's CEO does not expect the consumer to be in a much better place over the next 12 to 18 months
Real wages are falling: 3% pay growth against 3.4% inflation leaves a gap of roughly 0.4 percentage points
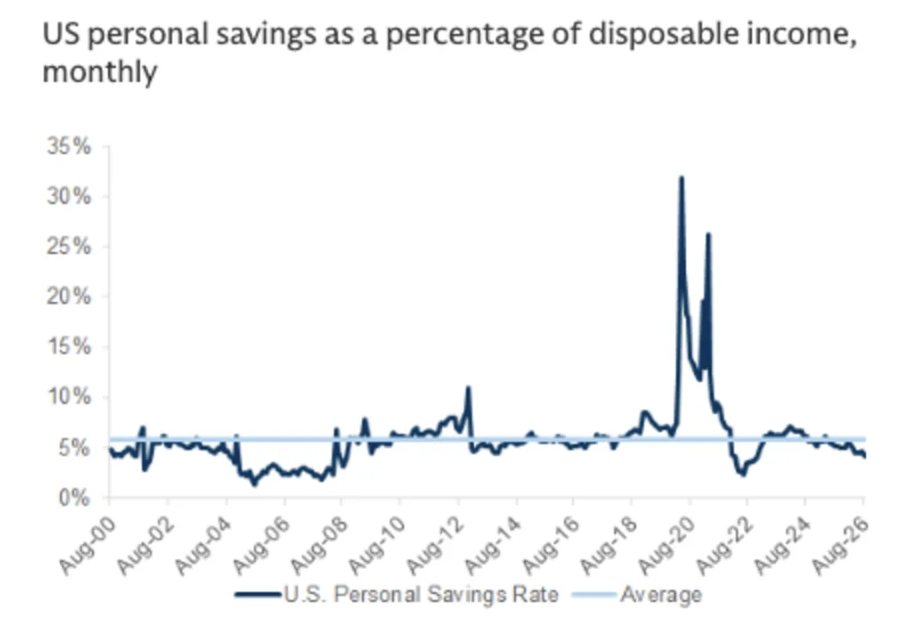
Saving rates on the decline. Goldman Sachs.
With midterms approaching, Americans’ confidence in the economy is in a tailspin (CNN, 4 minute read)
The University of Michigan's consumer sentiment index fell to a preliminary 46.3 in October from 48.1 in September, which would be the second-lowest reading in 74 years if it holds, with five of the lowest readings on record coming this year. The current-conditions measure fell 12.2% to an all-time low of 44.7, with the biggest declines among lower-income consumers and those with little stock market exposure. Year-ahead inflation expectations rose to 4.7% from 4.6%, up from 3.4% in February, and September CPI, due next Wednesday, is expected to show inflation rising to 3.6%, a four-month high. Spending has held up because of a "K-shaped" economy: the top 20% of households, with incomes of $155,000 or more, hold over 70% of wealth and drive 40% of spending, leaving growth vulnerable to a stock market correction
73% of respondents say it is a bad time to buy a household appliance, 78% a vehicle, and 87% a home
Only 35% said in September that the government was doing a good job on the economy, versus 62% in March
The reading lands just before the midterm elections and is seen as a negative signal for Republicans
IPO & EXITS
Nvidia-backed Aussie AI firm Firmus withdraws historic IPO, citing market volatility (CNBC, 3 minute read)
Nvidia-backed Australian AI data center operator Firmus has withdrawn its planned mega IPO, citing market volatility and conditions, after its board concluded the offering terms did not reflect the strength of its business and long-term growth outlook. The company had reportedly planned to raise $5 billion at A$11 per share, which would have been the second-largest new share sale in Australian history and valued Firmus at around $30.6 billion. Firmus will now pursue private capital and consider other public and private options. The decision follows an August $2 billion funding round backed by Nvidia, Coatue Management, Blackstone, and Jane Street, which lifted total equity raised over the past year above $3 billion and its valuation above $10.5 billion, and agreements last month to provide Meta with GPU computing capacity in Southeast Asia
Firmus said proceeding "was not in the best interests of the company and its shareholders"
The Meta agreements cover AI research, model development, and training at Firmus's Southeast Asia data centers, built on Nvidia's DSX platform
The withdrawal follows Oura's postponement of its own IPO last week, adding to signs of IPO market caution
Anthropic will be ‘most ridiculous IPO’ of year, analyst says (CNBC, 6 minute read)
Independent research firm New Constructs valued Anthropic at just $150 billion, against the $2 trillion market cap it is reportedly targeting, calling the offering the "most ridiculous IPO of 2026." The firm estimates Anthropic would need to earn double Nvidia's trailing-year net income of more than $190 billion to justify that valuation, while Anthropic's 2025 revenue was $4.6 billion with a $42 billion net loss, per a leaked prospectus. New Constructs concluded "we don't think Anthropic has a viable business," citing mounting losses and open-source competition, and argued the IPO is meant to give liquidity to Wall Street backers. Founder David Trainer has a mixed record as an IPO bear: he correctly called WeWork in 2019 but was wrong on DoorDash, now an $83 billion company
Anthropic claimed in July that annualized revenue rose sevenfold year over year to $65 billion
New Constructs has not seen the actual prospectus and relied on reported figures
Anthropic did not respond to a request for comment
Global M&A Report (PitchBook, 15 minute read)
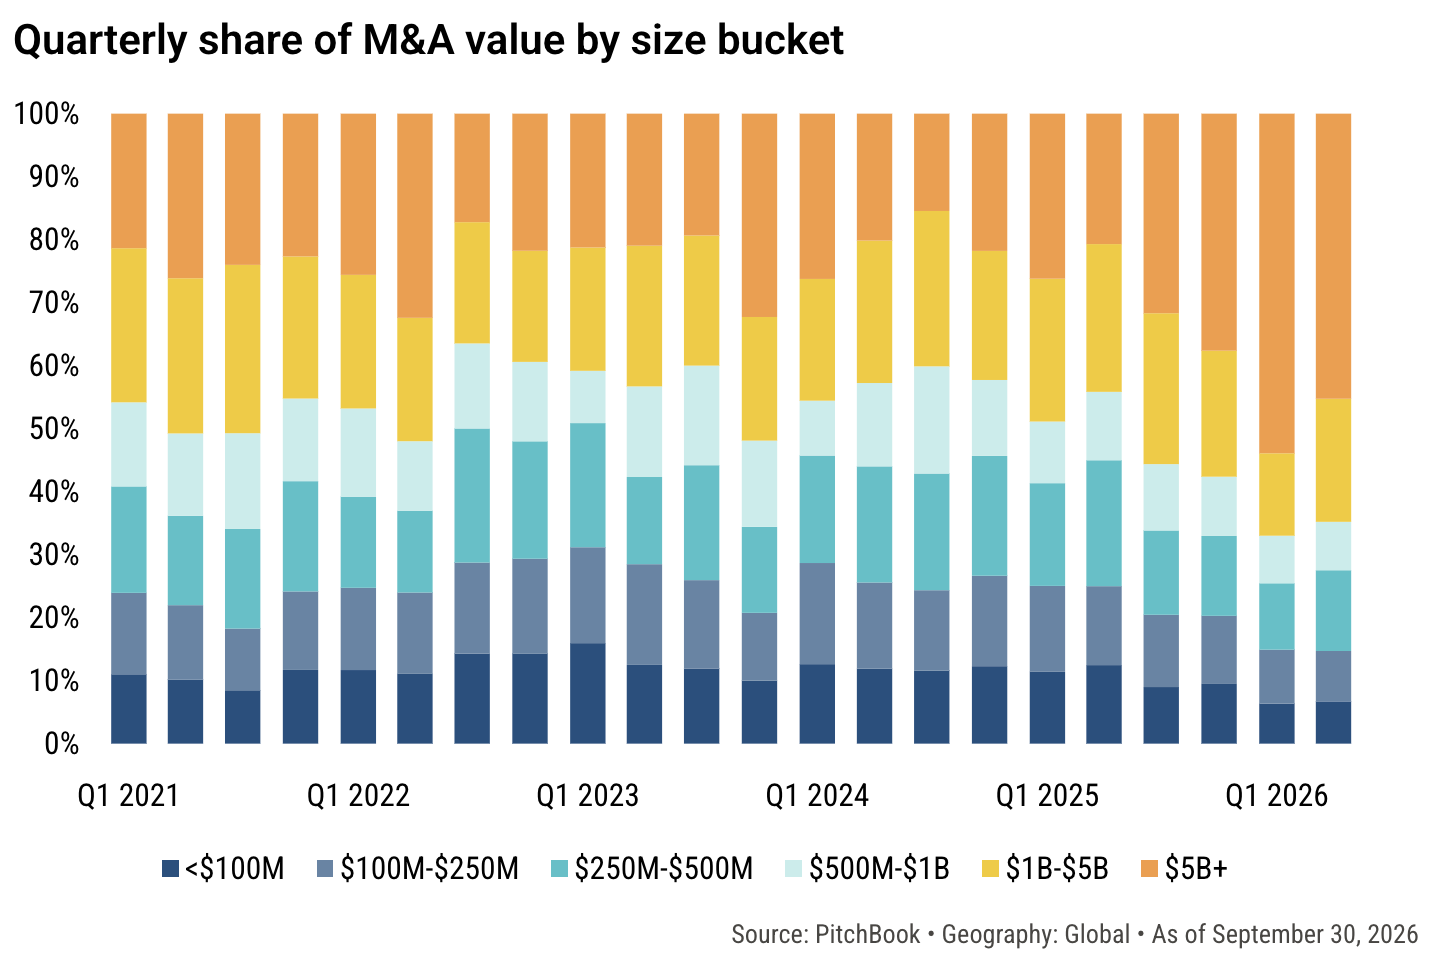
Global M&A slowed in Q3 from the record pace of the past four quarters, though deal value still topped $1 trillion for a fifth straight quarter. Deal count slipped to more than 11,700, below the 12,000-plus seen in recent quarters, and megadeals shrank: deals above $5 billion made up 21% of value, down from 42.9% in Q2 and 52.3% in Q1, with Prologis' $18.8 billion acquisition of SEGRO the largest. Corporate buyers pulled back sharply, with deal value falling 42.1% quarter over quarter to $601.5 billion. Even so, 2026 remains on pace for a record year, with M&A already above $4 trillion across more than 36,000 deals, implying a full-year total of $5.5 trillion
Only the third year on record to reach $4 trillion in deal value, with a full quarter still to go
Strategic buyers still did most of the buying, but the gap with financial sponsors narrowed
The decline is not seen as a concern, since it follows a record run that set a high bar
8alpha.ai is an AI fintech transforming cash-generating businesses into scalable, AI-powered companies. We provide revenue-based financing and hands-on AI transformation, delivering no zeros with unlimited upside. We’re the architects building financial infrastructure for the next generation of investors and startups.
Become part of our revolution.
Happy reading,
8alpha.ai’s Research & Investment Team